First Time Hiring a Professional? Hourly or Fixed Price, and Who Pays When It Runs Long
Hourly, fixed price, day rate and cost plus each move overrun risk to a different party, and the difference between a good engagement and a barely adequate one is written down before work starts.
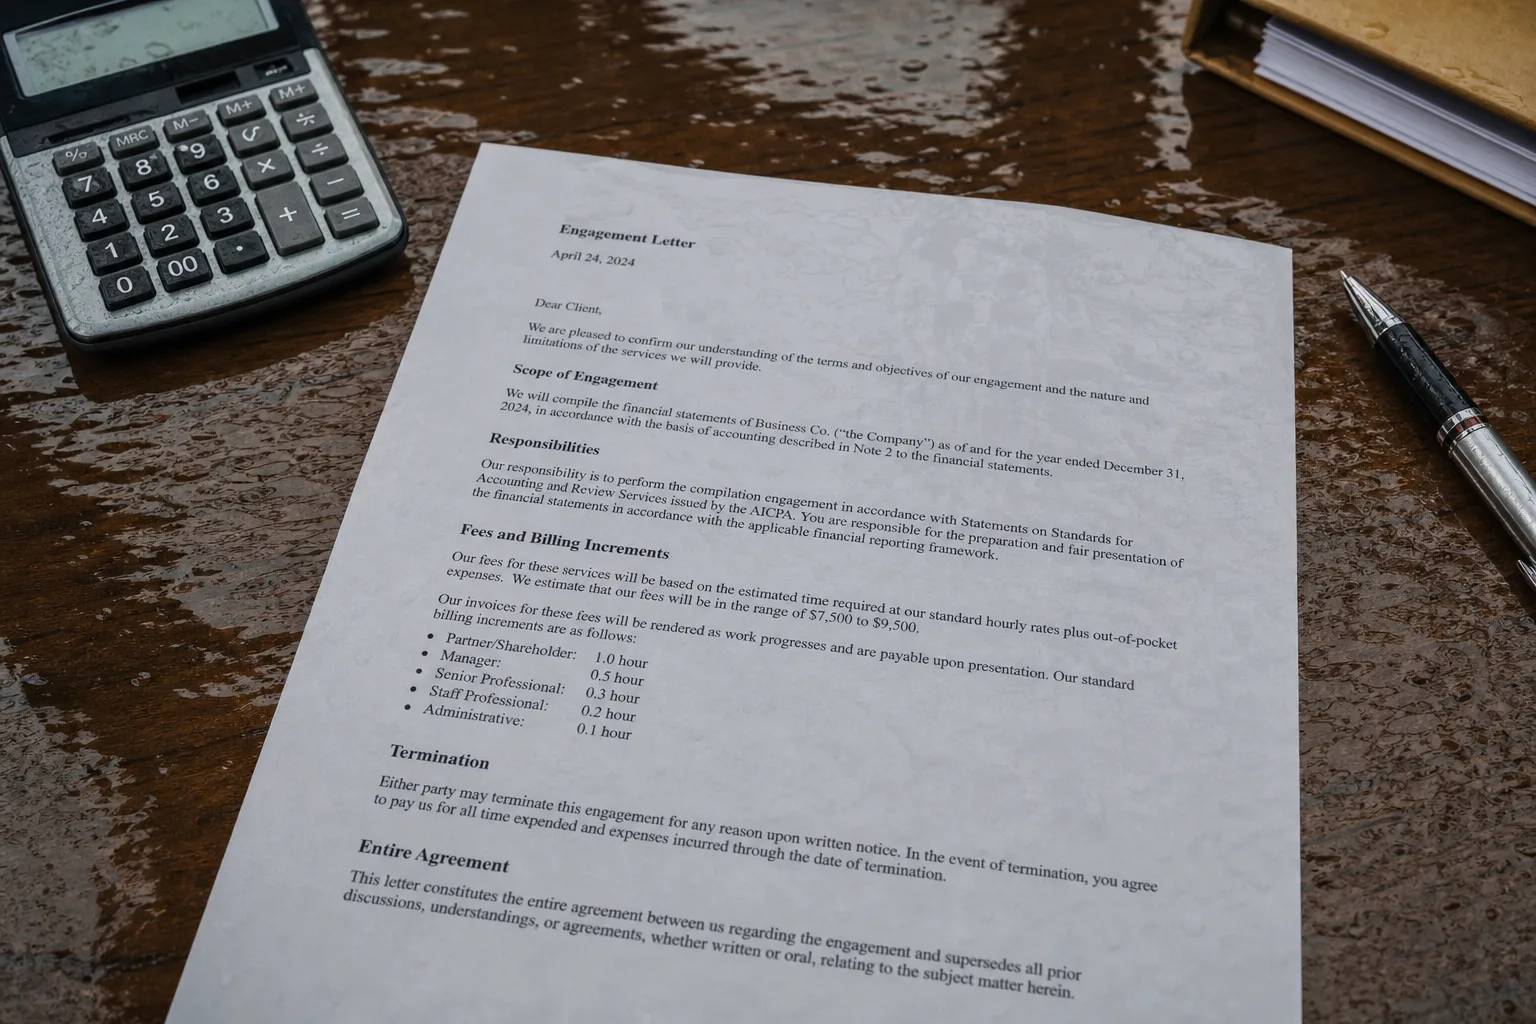
The first invoice from a professional firm is usually where a first-time buyer learns what they actually agreed to. Someone quoted a rate, the work started, and six weeks later a number arrived that bore no obvious relationship to anything discussed in the meeting. The rate was not the problem. The problem is that a rate prices an input, not a result, and nobody in the room said out loud who was carrying the risk that the work took twice as long as expected. That single question separates a well-run engagement from one that merely finished.
Four models, four different people holding the risk
Hourly billing puts the overrun on you. The firm is paid for effort, so if the analysis is harder than anyone thought, the discovery messier, the third party slower to respond, your bill grows and the firm's margin does not shrink. Fixed price reverses it: the firm quoted a number for a defined result and absorbs the extra hours, which is why fixed quotes carry a cushion and why a fixed-price firm will fight hard about what is inside the scope. A day rate sits close to hourly but with coarser units, and it rewards you for keeping the professional busy on days you have bought. Cost plus, where you pay documented costs and an agreed markup, is the most transparent and the least predictable, and it belongs in work where the shape of the job genuinely cannot be known in advance.
None of these is the honest one and none is the trap. They are four different answers to the same question, and the answer that suits you depends on whether you can define the outcome tightly enough for someone to price it.
What a good engagement writes down that a barely adequate one leaves verbal
A barely adequate engagement gets you a rate, a start date and a handshake. A good one gets you a description of the deliverable specific enough that both sides would agree, looking at the finished thing, whether it had been delivered. That is the whole test. If the engagement letter says the firm will advise on your entity structure, you have bought an unbounded conversation; if it says the firm will deliver a written recommendation covering two named alternatives, the tax treatment of each, and the filings required in your state, you have bought something with an edge. Edges are what make fixed prices possible and hourly bills reviewable.
The second thing worth writing down is the change mechanism. Work moves. New facts appear, a counterparty behaves unexpectedly, you change your mind about what you want. A good agreement says what happens then: who has to authorize additional work, in what form, and above what dollar threshold nothing proceeds without a fresh approval. First-time buyers often skip this because it feels like planning for conflict. It is the opposite. It is the clause that prevents the conversation where you insist you never asked for something and the firm produces time entries showing you did.
Estimates, caps and the difference between them
An estimate on hourly work is not a price. It is a forecast, and a forecast is worth exactly as much as the assumptions printed beneath it. What converts an estimate into something you can plan around is a cap, sometimes called a not-to-exceed, under which the firm bills hourly up to a ceiling and comes back to you before crossing it. That structure gives you the fairness of paying for actual effort and the protection of a known worst case, and competent firms offer it without being pushed. Ask what the assumptions behind the estimate are, and ask which of them, if wrong, would move the number most.
Watch the billing increment as well. Six-minute increments and fifteen-minute increments produce meaningfully different bills across hundreds of short tasks, particularly emails and calls. Ask who will actually do the work and at what rate, because a blended rate quoted by a partner can conceal a great deal of junior time, or a great deal of partner time you did not need. The Bureau of Labor Statistics tracks wages across professional and technical occupations, and the spread between seniority levels within a single firm is wide enough to explain most surprising invoices on its own.
How to choose, the first time
If you can describe the finished result in a paragraph, buy the result. Fixed price on a well-defined deliverable transfers the estimating risk to the party with the experience to estimate, which is the firm, and it makes your budget real. If you cannot describe it yet, buy a small, bounded piece of hourly work whose only purpose is to produce that description: a scoping engagement, a few paid hours, a written summary of what the real job involves. Then price the real job properly. Paying twice at the start is cheaper than open-ended billing on a job nobody understood.
The firms worth hiring will discuss all of this without defensiveness, because they have had the argument before and would rather have it now. Ask which model they would choose if they were paying, and why. The answer tells you a great deal about how the work will be run.